Infinite banking is a strategy where individuals use permanent life insurance policies to create a private, tax-advantaged source of liquidity for retirement. Instead of relying solely on market-linked investments, policyholders borrow against the cash value of their policies to fund expenses. This approach offers stability and control, allowing you to act as your own bank. Generational Wealth Concepts helps families design these strategies to ensure long-term financial security.
Defining the Infinite Banking Concept
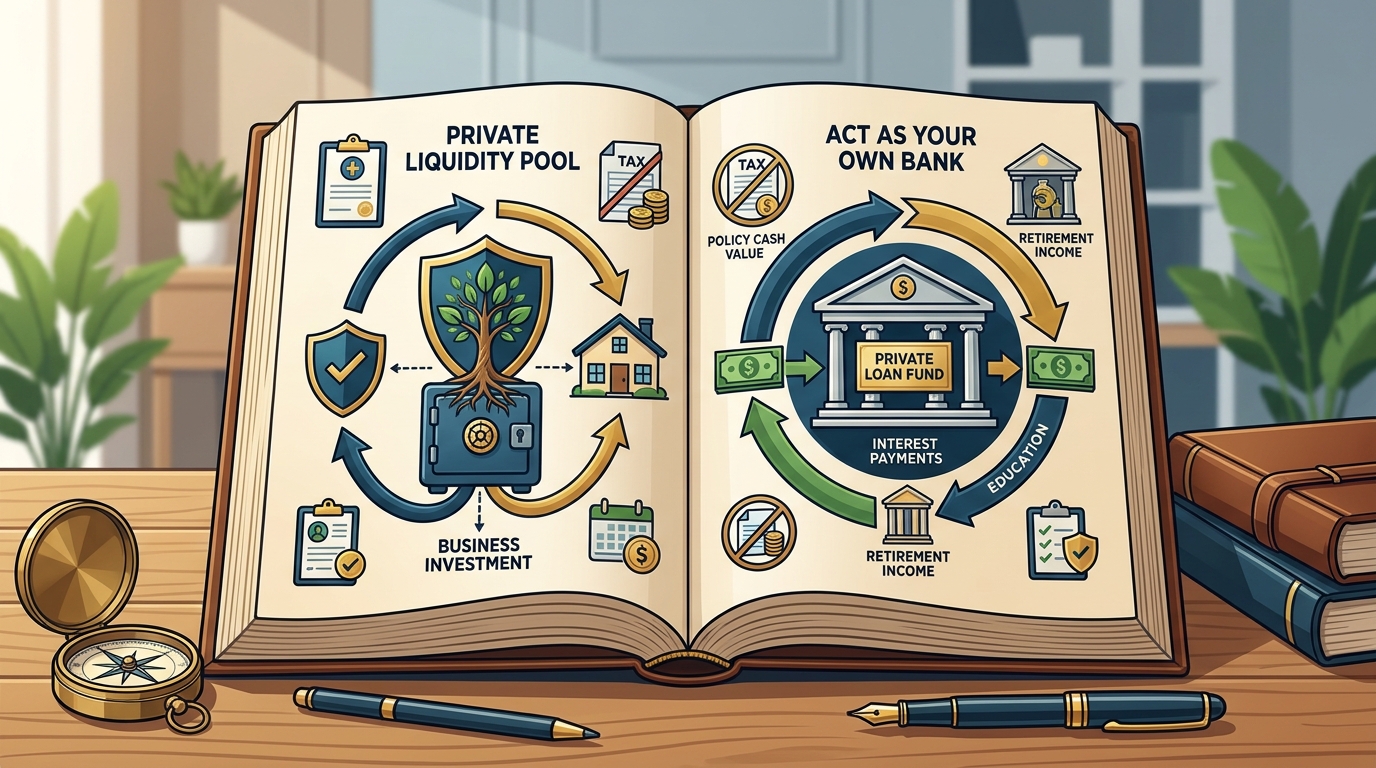
Infinite banking is a wealth management strategy that utilizes the cash value of permanent life insurance policies as a personal credit line. It is distinct from traditional banking because the "bank" is the insurance policy itself, which grows tax-deferred. The core mechanism involves overfunding a policy to build a substantial cash value reserve. This reserve can then be accessed through policy loans, which are not considered taxable income in most jurisdictions.
The strategy relies on the principle of compounding growth within a tax-protected environment. Unlike a 401(k) or IRA, where withdrawals are taxed as income, policy loans are generally tax-free. This distinction is critical for retirees who wish to supplement their income without increasing their tax burden. By treating the policy as a financial asset rather than just a death benefit, individuals can create a flexible resource for major expenses or daily living costs.
How the Mechanism Works in Practice
The operational workflow begins with the selection of a specific type of permanent life insurance, typically whole life or universal life. These policies are designed to accumulate cash value over time. The policyholder pays premiums that are higher than the minimum required to keep the policy in force. This excess premium accelerates the growth of the cash value component.
Once the cash value reaches a sufficient level, the policyholder can take out a loan against it. The loan is secured by the cash value of the policy. Interest is charged on the loan, but it is paid to the policyholder's own cash value account. This creates a unique dynamic where the interest paid on the loan contributes to the growth of the policy. The policy remains in force as long as the cash value is sufficient to cover the loan balance and interest.
Applying the Strategy to Retirement Income
The tax efficiency of this approach is a major advantage. Social Security benefits and pension income are often taxable. Adding policy loan proceeds to this income can push retirees into higher tax brackets. However, because policy loans are generally not considered income, they do not increase the taxable income base. This allows retirees to maintain their standard of living without the associated tax penalty. Generational Wealth Concepts coordinates with tax professionals to ensure this strategy aligns with individual tax situations.
Another benefit is the predictability of cash flow. Market returns are uncertain, but the growth of a permanent life insurance policy is guaranteed by the insurer. This provides a stable foundation for retirement planning. Retirees can model their income needs with greater confidence, knowing that a portion of their funds is protected from market fluctuations. This stability is particularly valuable for those who have experienced significant market losses in the past.
Risks and Considerations for Policyholders
Another consideration is the opportunity cost. Premiums for overfunded life insurance policies are typically higher than those for term life insurance or investment accounts. Retirees must weigh the tax benefits and liquidity of the policy against the potential returns of other investment vehicles. The strategy requires careful management and regular monitoring to ensure the policy remains in force and the cash value grows as expected.
It is also important to understand that the interest rate on policy loans is set by the insurance company. This rate can change over time, affecting the cost of borrowing. Policyholders should review their policy terms regularly to understand how interest rate changes may impact their strategy. Generational Wealth Concepts provides ongoing support to help clients monitor and adjust their policies as needed.
Implementation Steps for Success
Implementing an infinite banking strategy requires a structured approach. The first step is to assess your current financial situation and retirement goals. This includes evaluating your existing retirement accounts, income sources, and tax situation. A clear understanding of your needs will help determine the appropriate size and type of policy.
The second step is to select a suitable insurance carrier and policy type. Not all permanent life insurance policies are created equal. Some are designed specifically for wealth accumulation, while others focus primarily on death benefits. It is important to choose a policy that aligns with your goals and has a strong track record of cash value growth. Generational Wealth Concepts works with multiple carriers to find the best fit for each client.
The final step is to develop a loan management plan. This plan should outline how and when you will take out loans, how you will manage the interest, and how you will repay the loans. A well-structured loan management plan is essential to prevent policy lapse and maximize the benefits of the strategy. Regular reviews with your insurance professional will help ensure that the strategy remains aligned with your evolving financial needs.
Key Takeaways
- Infinite banking uses permanent life insurance cash value as a tax-advantaged source of retirement income.
- Policy loans are generally tax-free, allowing retirees to access funds without increasing taxable income.
- The strategy provides stability and protection against market volatility, preserving investment principal.
- Overfunding the policy accelerates cash value growth, creating a larger reserve for borrowing.
- Policy lapse is a significant risk if cash value does not grow as projected or loans are mismanaged.
- Opportunity cost must be considered, as premiums are higher than term life or standard investment accounts.
- Regular monitoring and professional guidance are essential to maintain the policy and optimize the strategy.
Frequently Asked Questions
Is infinite banking the same as privatized banking?
Infinite banking and privatized banking are related but distinct concepts. Infinite banking focuses on using life insurance cash value for personal liquidity. Privatized banking often involves a broader strategy that may include multiple insurance policies and business structures to create a private banking system. Both strategies aim to provide tax-advantaged liquidity, but privatized banking is typically more complex and involves a larger scale of assets.
Can I use infinite banking for business expenses?
Yes, policy loans can be used for business expenses. However, the tax treatment may differ depending on how the loan is used and the structure of the business. If the loan is used for a business purpose, it may be deductible as a business expense. It is important to consult with a tax professional to understand the specific implications for your situation.
What happens if I die with an outstanding policy loan?
If you die with an outstanding policy loan, the loan balance is deducted from the death benefit. The remaining amount is paid to your beneficiaries. This means that the death benefit is reduced by the amount of the loan. It is important to consider this impact when planning your estate and ensuring that your beneficiaries receive the intended amount.
How long does it take to build sufficient cash value?
Is infinite banking suitable for everyone?
Infinite banking is not suitable for everyone. It requires a long-term commitment and higher premiums than term life insurance. It is best suited for individuals who have a stable income, a long time horizon, and a need for tax-advantaged liquidity. Those with limited budgets or short-term goals may find other strategies more appropriate. A professional assessment can help determine if this strategy fits your specific financial situation.
Conclusion
The infinite banking concept offers a powerful tool for retirement income planning. By leveraging the cash value of permanent life insurance, individuals can create a stable, tax-advantaged source of liquidity. This strategy provides protection against market volatility and helps preserve wealth for future generations. Generational Wealth Concepts is dedicated to helping you navigate this complex strategy with confidence. Our team works with you to design a personalized plan that aligns with your goals and ensures long-term financial security.
To explore how infinite banking can fit into your retirement strategy, contact our team. We will review your current financial situation and help you determine if this strategy is right for you. Take the first step toward a more secure financial future today.