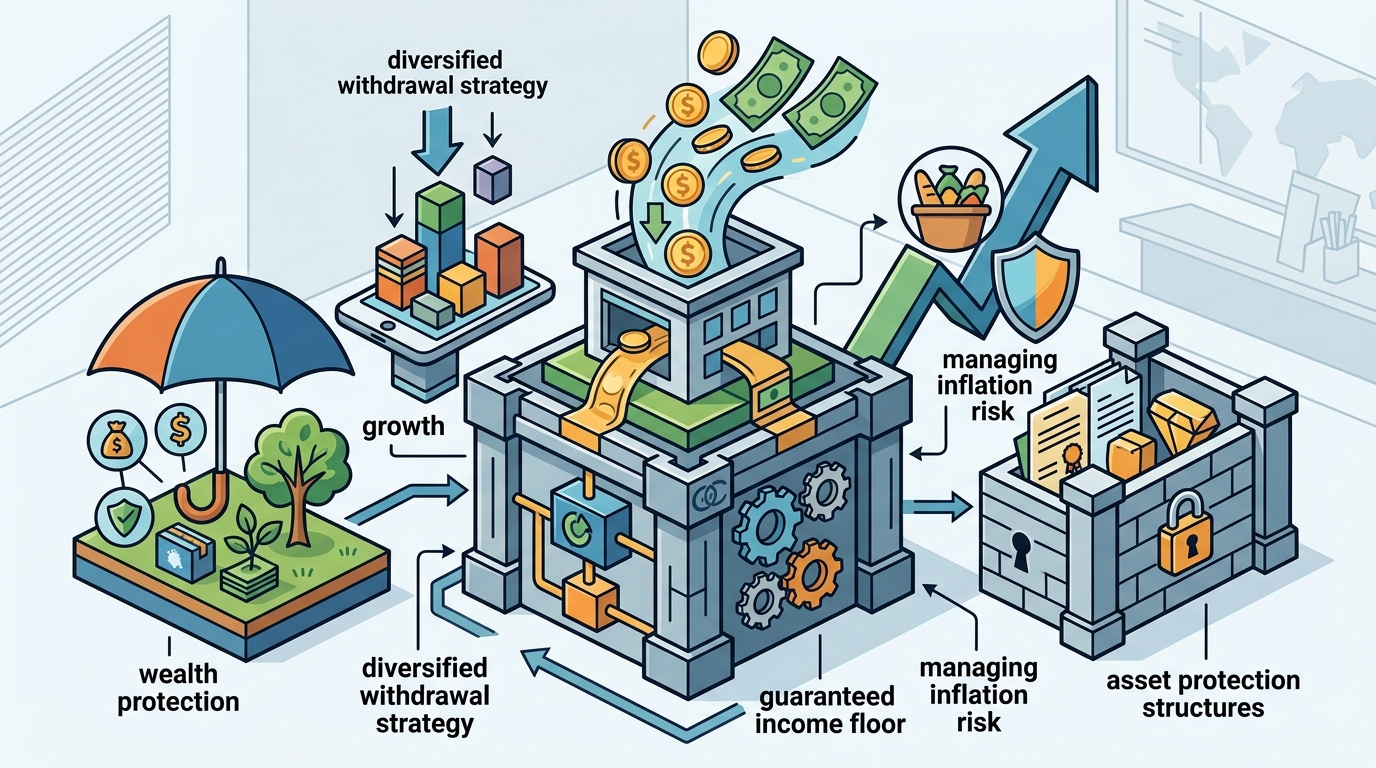
Protecting wealth and creating reliable retirement income requires a coordinated strategy that balances growth, safety, and cash flow. Generational Wealth Concepts helps individuals, families, and business owners design plans that address these core needs. This guide covers four essential pillars: building a guaranteed income floor, implementing a diversified withdrawal strategy, managing inflation risk, and utilizing asset protection structures. We will explore how insurance and annuity strategies can work together to secure your financial future.
Building a Guaranteed Income Floor
The primary fear for many retirees is outliving their savings. A guaranteed income floor is a baseline level of monthly cash flow that is contractually secured and not dependent on market performance. This foundation provides psychological stability and covers essential living expenses. By establishing this floor, you reduce the amount of money you need to withdraw from volatile investment accounts.
The Role of Annuities
Annuities are financial contracts that can convert a lump sum of savings into a stream of payments. At Generational Wealth Concepts, we evaluate whether an annuity fits your specific retirement goals. Fixed annuities offer steady, predictable interest rates with principal protection. Fixed Indexed Annuities (FIAs) provide growth potential linked to a market index while protecting your account value from negative index performance. Income annuities allow you to turn a portion of your savings into a monthly retirement paycheck for life.
Assessing Your Current Fit
Not all annuities are created equal. An annuity that was a good fit when you purchased it may not be the best fit today. The real question is whether your current annuity still fits what you are trying to accomplish for growth, income, protection, and legacy. We can review your existing policies to help you understand whether they still align with your retirement goals. If you are unsure, our team can help you determine if a guaranteed income floor makes sense for part of your retirement assets.
The Diversified Withdrawal Strategy
Retirement planning is about more than growing money. It is about turning what you have built into income you can rely on while protecting against the risks that can disrupt the plan. A diversified withdrawal strategy involves using multiple sources of income to meet your needs. This approach ensures that no single asset class or account type bears the entire burden of your cash flow requirements.
Coordinating Income Sources
We help clients look at how Social Security, pensions, annuities, and other income sources can work together. The goal is not to force everything into one product or account. Instead, we decide what each part of your money needs to do. Some assets may be positioned for long-term growth, while other money may need more stability or predictable income. This coordination helps identify the issues that deserve attention in your overall plan.
Market Risk and Sequence of Returns
A major market decline early in retirement can be especially uncomfortable when you are also taking withdrawals. This is known as sequence of returns risk. We can help you look at how much of your retirement income depends on market performance. Adding protected or predictable income can help you feel more confident about the plan. The right approach depends on your income needs, time horizon, liquidity needs, and overall retirement strategy.
Managing Inflation Risk
Inflation erodes the purchasing power of your money over time. A diversified withdrawal strategy must account for this reality. While fixed products offer safety, they may not keep pace with rising costs. Therefore, a balanced plan often includes components that offer growth potential to combat inflation.
Growth Potential with Protection
Fixed Indexed Annuities (FIAs) are often used to address this need. They offer growth potential linked to a market index while protecting your account value from negative index performance. This allows your money to participate in market gains without suffering from market losses. We help you determine the appropriate allocation of growth-oriented assets within your protected portfolio. This balance is crucial for maintaining your standard of living over a long retirement.
Tax-Deferred Earnings
Tax-deferred earnings are a key feature of many annuity and insurance strategies. By deferring taxes on investment gains, you allow your money to compound more efficiently. This can be particularly beneficial when you are in a higher tax bracket during your working years. We help you understand the tax implications of different withdrawal strategies. This ensures that your plan is not only safe but also tax-efficient.
Asset Protection and Liquidity
Protecting your wealth from unexpected events is just as important as generating income. Asset protection structures help ensure that your savings remain available for your needs and your legacy. These structures can provide liquidity for opportunities or major purchases while maintaining long-term protection.
Privatized Banking Strategies
Privatized banking uses a properly structured permanent life insurance policy to combine life insurance protection with access to policy cash value. For the right person, it can create another source of liquidity and financial flexibility. When properly structured, policy cash value may provide a source of funding for opportunities or major purchases. It is important to note that policy loans accrue interest and can reduce cash value and death benefits if not repaid. We help clients evaluate whether this strategy aligns with their goals for protection, income, liquidity, and legacy.
Long-Term Care Considerations
An extended need for care can affect retirement income, savings, a spouse's financial security, and what may ultimately be left for family. Planning ahead can help you protect your assets from the high costs of long-term care. We help clients compare traditional long-term care insurance, life insurance with long-term care or chronic-illness benefits, and other available strategies. The objective is to understand the tradeoffs before a care need arises. This ensures that your retirement plan remains robust even in the face of health challenges.
Key Takeaways
- A guaranteed income floor provides a baseline of cash flow that is not dependent on market performance.
- A diversified withdrawal strategy uses multiple income sources to reduce risk and ensure sustainability.
- Inflation protection requires a balance between safety and growth potential within your portfolio.
- Asset protection structures, such as privatized banking, can provide liquidity while maintaining long-term protection.
- Long-term care planning is essential to prevent care costs from depleting your retirement savings.
- Regular reviews of your insurance and annuity strategies are necessary to ensure they still fit your current goals.
- Coordinating with specialized professionals for tax, legal, and estate planning advice can enhance your overall strategy.
- Generational Wealth Concepts helps you design a plan that balances growth, safety, and cash flow.
Frequently Asked Questions
How do I know if my retirement income will last?
It starts with understanding what income you will need, which expenses are essential, how long retirement may last, and how much of your income depends on market performance. We help you look at your available income sources and evaluate whether insurance or annuity strategies could add more predictability to the plan.
What is privatized banking?
Privatized banking uses a properly structured permanent life insurance policy to combine life insurance protection with access to policy cash value. For the right person, it can create another source of liquidity and financial flexibility.
How can I create retirement income I cannot outlive?
Some retirement strategies can provide income designed to continue for life. The right approach depends on your existing Social Security or pension income, expenses, savings, need for access to money, and other goals. We can help you evaluate whether creating a guaranteed income floor makes sense for part of your retirement assets.
What happens if the market drops right after I retire?
A major market decline early in retirement can be especially uncomfortable when you are also taking withdrawals. We can help you look at how much of your retirement income depends on market performance and whether adding protected or predictable income could help you feel more confident about the plan.
Should all of my retirement money be exposed to the market?
That depends on the role each part of your money needs to play. Some assets may be positioned for long-term growth, while other money may need more stability or predictable income. We help you look at how much of your retirement plan depends on market performance and whether protected strategies deserve a role alongside other assets.
How do I know if I have a good annuity or a bad one?
An annuity is not good or bad simply because of its product type. What matters is whether its guarantees, fees, surrender period, income features, growth potential, and access to money still fit what you need it to accomplish. We can review an existing annuity and help you understand what you own before you decide whether any change makes sense.
How can long-term care affect my retirement plan?
An extended need for care can affect retirement income, savings, a spouse's financial security, and what may ultimately be left for family. Planning ahead can help you protect your assets from the high costs of long-term care. We help clients compare traditional long-term care insurance, life insurance with long-term care or chronic-illness benefits, and other available strategies.
Next Steps for Your Plan
Building a retirement strategy designed for income, protection, and legacy is a complex process. It requires a clear understanding of your goals and the tools available to achieve them. Generational Wealth Concepts helps individuals, families, and business owners create strategies for retirement income, annuities, life insurance, long-term care, and legacy planning. We also coordinate with specialized professionals when tax, estate-planning, or investment advice is needed. To begin your journey toward financial confidence, schedule a retirement strategy review with our team. We will discuss your priorities, identify areas that may deserve attention, and determine appropriate next steps.