Debt Protection Insurance for Small Business Owners: A Wealth Protection Guide
Small business owners should use mortgage or debt protection insurance to prevent personal assets from being seized to satisfy business liabilities. This guide covers how these policies protect business continuity, prevent asset seizure, shield family liabilities, and preserve working capital. It explains the specific insurance mechanisms that keep your personal wealth separate from your business risks.
Business Continuity Protection
Business continuity protection is the strategy of ensuring your company can survive the loss of a key owner or operator. For small business owners, the business itself is often the largest asset. If you pass away or become disabled, the business may face immediate financial distress. Debt protection insurance helps maintain the cash flow needed to keep the business running.
The Role of Key Person Insurance
Key person insurance is a policy taken out by the business on the life of a critical employee or owner. If the insured person dies, the business receives the death benefit. This payout can be used to pay off business debts, buy out the deceased owner's share, or fund a search for a replacement. This prevents the business from collapsing due to a sudden loss of leadership or expertise.
Debt Coverage for Operational Stability
Many small businesses operate with significant debt, including lines of credit, equipment loans, and commercial mortgages. If the primary owner is no longer able to manage the company, lenders may call in these debts. A debt protection strategy ensures that these obligations are met without draining the business's operating accounts. This stability allows the remaining owners or family members to manage the transition without the pressure of immediate debt repayment.
Asset Seizure Prevention
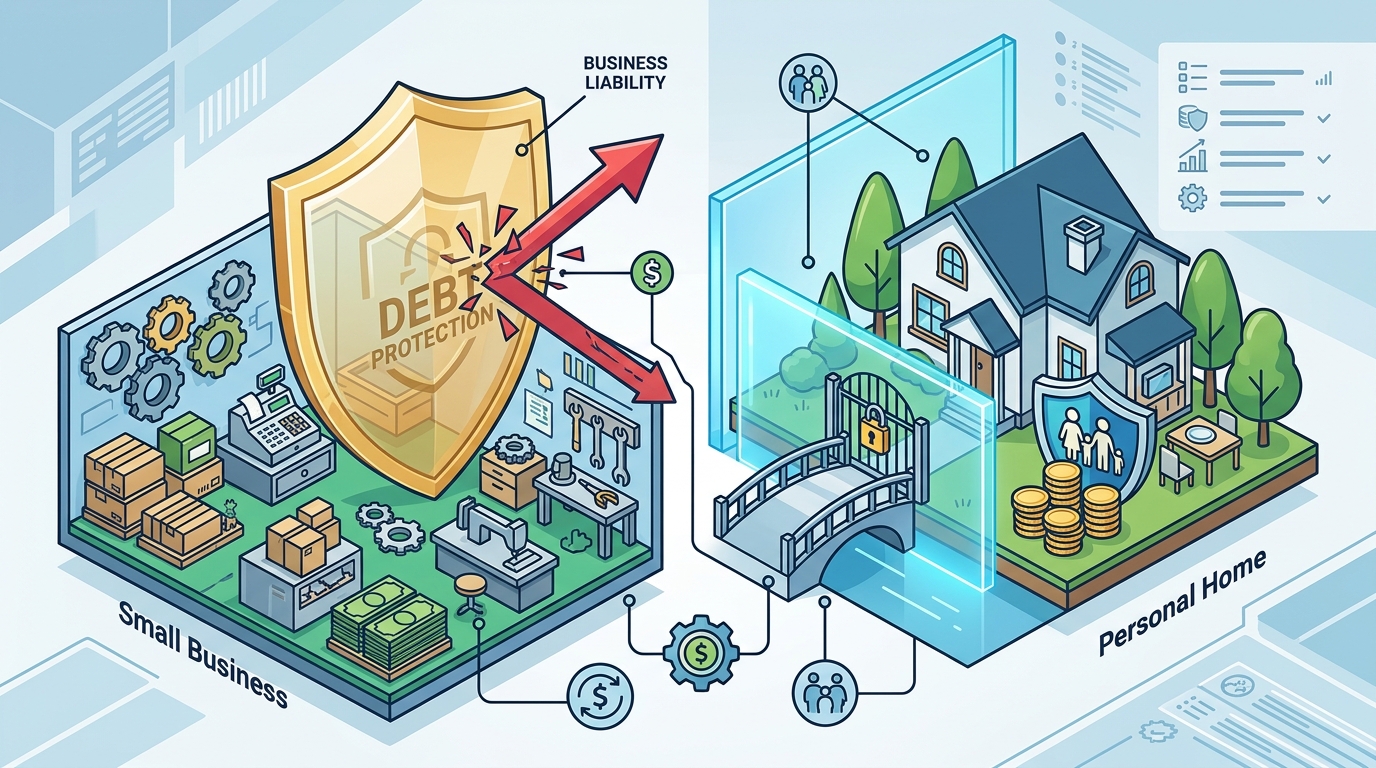
Asset seizure prevention is the legal and financial process of protecting personal and business assets from creditors. In many business structures, such as sole proprietorships or general partnerships, personal assets are not fully separated from business liabilities. If the business fails or faces a lawsuit, creditors may seek to seize personal assets, including your home and savings.
Personal Guarantees and Risk
Small business owners often sign personal guarantees for business loans. This means you are personally responsible for the debt if the business cannot pay. If the business fails, the lender can pursue your personal assets to satisfy the remaining balance. Debt protection insurance can provide the funds to pay off these guaranteed debts, preventing the seizure of your personal property.
Protecting the Family Home
Your home is often your most valuable personal asset. Without proper protection, a business failure could force you to sell your home to pay off business debts. By using life insurance or disability income insurance to cover business liabilities, you create a financial buffer. This buffer ensures that your family home remains secure, even if the business encounters significant financial difficulties.
Family Liability Protection
Family liability protection is the practice of ensuring that your family's financial security is not compromised by business risks. When you run a small business, your personal and family finances are often intertwined. A business failure can lead to a loss of income, which directly impacts your family's ability to meet their needs.
Income Replacement for the Family
If you are the primary earner, your death or disability can leave your family without income. Disability insurance is a policy that replaces a portion of your income if you cannot work due to illness or injury. This income replacement helps your family cover living expenses, mortgage payments, and other obligations. It provides a safety net that allows your family to maintain their lifestyle while you recover or while the business is being sold or closed.
Legacy and Estate Considerations
Debt protection also plays a role in legacy planning. If you pass away, your estate may be responsible for any remaining business debts. Life insurance can provide the liquidity needed to settle these debts without forcing the sale of other assets. This ensures that your family receives the inheritance you intended, rather than having to use it to pay off business liabilities. It is a critical component of a comprehensive wealth protection plan.
Working Capital Preservation
Working capital preservation is the strategy of maintaining sufficient cash flow to cover day-to-day business operations. Working capital is the difference between a company's current assets and current liabilities. It is essential for paying employees, suppliers, and other short-term obligations. If working capital is depleted, the business may struggle to operate, even if it is profitable in the long term.
The Impact of Debt on Cash Flow
Business debt requires regular payments, which reduces the cash available for operations. If the business faces a downturn or a loss of key personnel, these debt payments can strain the company's cash flow. Debt protection insurance can help preserve working capital by ensuring that debt obligations are met without drawing down operating cash. This allows the business to continue functioning smoothly during challenging times.
Strategic Use of Insurance Proceeds
When a debt protection policy pays out, the proceeds can be used strategically to preserve working capital. For example, the funds can be used to pay off high-interest debt, freeing up cash flow for other uses. Alternatively, the proceeds can be used to invest in the business, helping it to grow and become more resilient. This strategic use of insurance proceeds can help the business weather financial storms and emerge stronger.
Comparison of Protection Strategies
| Strategy | Primary Benefit | Best For |
|---|---|---|
| Key Person Insurance | Business continuity | Businesses reliant on a specific owner or employee |
| Disability Income Insurance | Personal income replacement | Owners who are the primary earners |
| Life Insurance for Debt | Debt payoff and asset protection | Owners with significant personal guarantees |
| Business Overhead Coverage | Operating expense coverage | Businesses with high fixed costs |
Key Takeaways
- Debt protection insurance prevents personal assets from being seized to satisfy business liabilities.
- Key person insurance helps ensure business continuity in the event of an owner's death or disability.
- Personal guarantees on business loans create a direct link between business failure and personal asset risk.
- Disability insurance provides income replacement to protect your family's financial security.
- Life insurance can provide the liquidity needed to settle business debts and protect your estate.
- Preserving working capital is essential for maintaining day-to-day business operations.
- A comprehensive wealth protection plan should include multiple types of insurance to cover different risks.
- Consulting with an independent insurance professional can help you design a strategy tailored to your specific business needs.
Frequently Asked Questions
What is debt protection insurance for small business owners?
Debt protection insurance is a combination of life, disability, and key person insurance policies designed to cover business debts and protect personal assets. It ensures that business liabilities are paid off if the owner dies or becomes disabled, preventing the seizure of personal property.
How does key person insurance differ from life insurance?
Key person insurance is owned by the business and pays the business if a key employee dies. Life insurance is owned by the individual and pays the individual's beneficiaries. Key person insurance is used for business continuity, while life insurance is used for personal and family protection.
Can disability insurance cover business debts?
Disability insurance replaces your personal income, which can be used to pay business debts if you are personally liable. It does not directly pay business debts, but it provides the cash flow needed to meet those obligations while you are unable to work.
What happens if I have personal guarantees on my business loans?
If you have personal guarantees, you are personally responsible for the debt if the business cannot pay. Debt protection insurance can provide the funds to pay off these debts, protecting your personal assets from seizure.
How much insurance do I need to protect my business debts?
The amount of insurance you need depends on the total value of your business debts and your personal assets. A general rule of thumb is to have coverage equal to the total amount of your business liabilities. An insurance professional can help you determine the appropriate coverage amount.
Is debt protection insurance expensive?
The cost of debt protection insurance varies based on factors such as your age, health, and the amount of coverage. While it is an additional expense, it is often a small fraction of the cost of losing your personal assets. It is a cost-effective way to protect your wealth.
Can I use life insurance to pay off my mortgage?
Yes, you can use life insurance to pay off your mortgage if you are personally liable for the debt. This is a common strategy for protecting your family home from being seized to satisfy business liabilities.
Where can I find an insurance professional who understands small business needs?
You can find an insurance professional who understands small business needs by looking for an independent agency that specializes in business insurance and wealth protection. Generational Wealth Concepts offers comprehensive insurance and retirement income strategies for small business owners.
Conclusion
Small business owners face unique financial risks that can threaten their personal wealth and family security. Debt protection insurance is a critical component of a comprehensive wealth protection plan. It helps ensure business continuity, prevent asset seizure, protect family liabilities, and preserve working capital. By understanding the specific risks associated with your business structure and liabilities, you can design an insurance strategy that protects your hard-earned wealth.
At Generational Wealth Concepts, we help small business owners create strategies for retirement income, protection, and legacy. We work with you to identify your specific risks and design a plan that addresses them. Schedule a free strategy session to learn how debt protection insurance can safeguard your business and your family's future.